A strong LBO IRR can hide a weak value-creation story. In lbo returns analysis, the headline return tells you what the equity earned, not whether it came from EBITDA growth, debt paydown or a higher exit multiple. IRR measures annualised return; MOIC compares cash proceeds with invested equity. Neither explains the source on its own.
That distinction matters when several assumptions move at once. EBITDA growth can increase enterprise value, while debt reduction increases the equity value left after debt. A changing multiple can amplify or offset those effects. Treating them as interchangeable makes the bridge from entry to exit hard to reconcile, and can make financing effects look like operating improvement.
This article explains how to build a transparent LBO returns attribution, calculate each driver’s contribution and test the assumptions behind the result. A worked example separates EBITDA growth, deleveraging and exit multiple movement, then reconciles the components to the change in equity value. You’ll also see why attribution depends on the method used and how to explain its limitations.
A strong IRR can look compelling in an LBO model, yet reveal little about which assumptions produced the return. IRR is the annualised rate of return on invested equity. MOIC, or multiple of invested capital, compares total equity proceeds with the original equity investment. Both measure the outcome, but neither explains its sources.
LBO returns analysis is a model-based bridge that separates the change in equity value into identifiable drivers, but it does not prove those drivers caused the investment return. To build that bridge, keep enterprise value and equity value distinct. Enterprise value represents the value of the business before deducting net debt. Equity value is what remains for shareholders after that deduction. Debt is central to a Leveraged buyout (LBO), but a reduction in debt is not the same as an increase in operating value.
Returns attribution decomposes the modelled change in equity value into components such as EBITDA growth, a change in the exit multiple and debt paydown. It shows how the model’s assumptions connect entry value to exit value. It is not a return metric like IRR or MOIC, and it cannot establish that a particular operating action caused the outcome. Treat it as an explanation of the model, not proof of investment causality.
Consider two hypothetical investments with the same 2.0x MOIC. In one, EBITDA grows while the exit multiple stays flat, with modest debt reduction. In another, EBITDA changes little, but the exit multiple rises and debt falls substantially. The equity outcome is the same, but the sources and risks differ. Growth depends on operating performance; multiple expansion depends on the valuation applied at exit; debt paydown depends on cash available to reduce borrowings. Separate these assumptions before interpreting the headline return.
Use the enterprise value formula to isolate operating and valuation effects: EV = EBITDA × valuation multiple. EBITDA growth and multiple movement change enterprise value; net debt movement affects the equity value derived from it. In an LBO returns analysis, keep these effects distinct so a fall in borrowings isn’t presented as growth in the operating business.
To measure EBITDA growth, hold the selected multiple constant. To measure multiple movement, apply the entry and exit multiples to a clearly defined EBITDA basis. If both EBITDA and the multiple change, state the calculation order because it affects how the interaction is allocated. Decompose EBITDA into volume, price, margin or other operating drivers only when the model contains assumptions that support those calculations. For example, a revenue growth assumption alone does not explain whether growth comes from higher volume, higher prices or both.
Calculate equity value consistently at both dates: equity value = enterprise value − net debt, with net debt defined as debt less cash. A reduction in net debt increases equity value, all else equal, but doesn’t increase enterprise value. Check that debt, cash and other adjustments use matching definitions. Show add-on acquisitions, dividends and recapitalisations separately when they affect enterprise value, sponsor contributions or cash returned, rather than burying them in routine operating or debt-paydown effects.
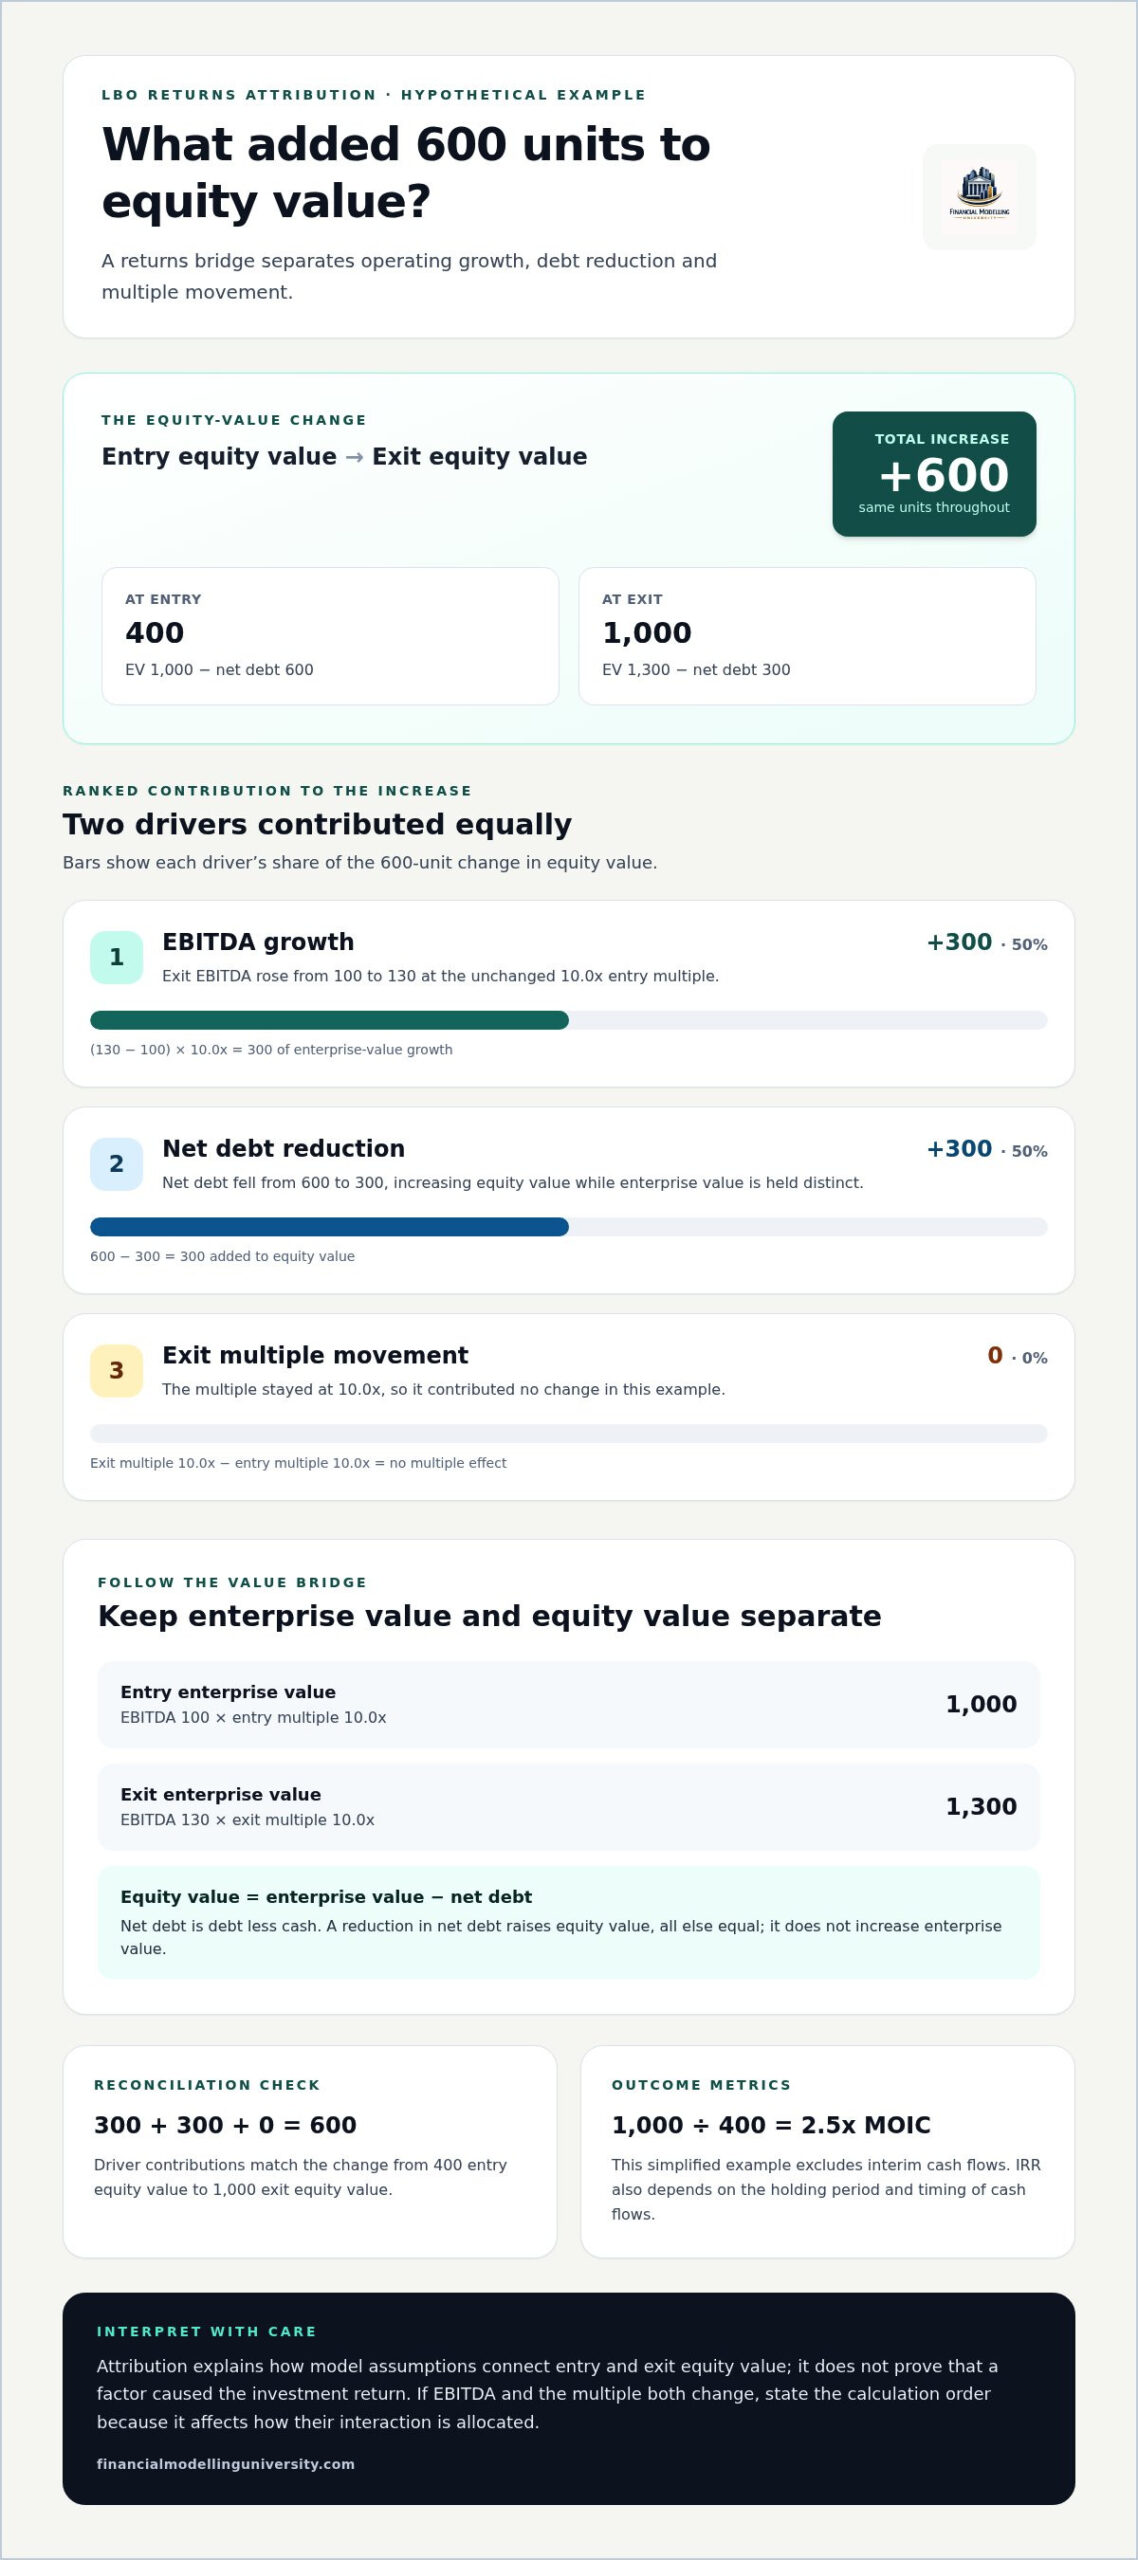
Use one consistent set of definitions for entry and exit EBITDA, valuation multiples, net debt and equity value. In this hypothetical example, all figures are in the same units. Entry EBITDA is 100, the entry multiple is 10.0x and entry net debt is 600.
If both EBITDA and the multiple change, the two effects interact. One clear convention is to calculate EBITDA growth at the entry multiple, then calculate multiple movement using exit EBITDA: (exit EBITDA − entry EBITDA) × entry multiple, followed by exit EBITDA × (exit multiple − entry multiple). This assigns the interaction to the multiple effect. State the convention, keep periods and debt definitions consistent, and disclose any residual from other adjustments.
In this simplified hypothetical case, exit equity value of 1,000 divided by initial equity value of 400 equals a 2.5x MOIC. In a full LBO model, make sure the equity amounts used for MOIC reflect the actual sponsor investment and proceeds, including any interim cash flows. IRR also depends on the holding period and timing of interim cash flows, which this simplified bridge excludes.
A returns bridge is only as reliable as the assumptions feeding it. Use it to explain the modelled change in equity value, not to claim that one factor caused the investment outcome. External market conditions, competitive pressure and execution risk can affect results without appearing as separate lines in the bridge.
The bridge allocates value changes under a defined set of assumptions. It doesn’t establish why EBITDA changed or prove that an operational initiative produced the forecast result. The calculation order also matters when EBITDA and the exit multiple both move: a different sequencing convention can allocate the interaction value differently between operating growth and multiple movement. Disclose the convention and treat attribution as an analytical explanation, not causal evidence.
Audit the key inputs against the operating model and debt schedule. Check that EBITDA uses the same definition and period at entry and exit, and verify both multiples against the correct EBITDA basis. Reconcile net debt to debt less cash using consistent definitions. Then confirm that cash flows, distributions and the holding period align with the return calculation.
In Excel, trace formulas rather than relying only on displayed outputs. Check signs, units and period alignment, then confirm that the driver contributions plus any disclosed residual reconcile to the total equity-value change. Use sensitivity analysis to test operating and exit assumptions separately, and compare the resulting driver contributions across cases. For example, hold the exit multiple constant in one case and vary it in another to see how much of the modelled change depends on valuation. This helps focus review on the assumptions that need the clearest support.
Make lbo returns analysis a repeatable step in your financial modelling workflow. In your next LBO, create a dedicated attribution tab, link it to the operating model and debt schedule, and make each key assumption easy to trace. Then run downside and upside cases. Check how the return changes when operating delivery weakens or exit conditions move, and identify which driver accounts for the difference.
Keep the explanation useful to its audience. A clear bridge helps a reviewer see which assumptions drive the result, where the model is most sensitive and what deserves closer scrutiny. It also makes updates easier: change an input, refresh the outputs and confirm the bridge still reconciles. Treat that discipline as part of the model, not a presentation step added at the end.
Build that discipline with structured LBO financial modelling practice. Explore Financial Modelling University courses, including LBO Financial Models.
In lbo returns analysis, attribution separates modelled sources of value creation; IRR measures the annualised, timing-sensitive return on invested equity. A model can calculate both, but the bridge alone cannot determine IRR without dated investments and interim cash flows. MOIC is different: it compares total invested capital with total value received, without accounting for when those cash flows occur.
Two LBOs can show the same MOIC but different IRRs because MOIC ignores timing, while IRR annualises dated cash flows. Receiving the same proceeds earlier produces a higher IRR than receiving them later. Interim distributions can also change the result, even if total proceeds are unchanged. Compare each investment date, distribution date and final exit date before interpreting returns.
In the model, a higher exit multiple increases enterprise value if EBITDA is unchanged. But that uplift reflects the valuation assumption, not necessarily better operations. Check that entry and exit multiples use comparable EBITDA definitions and periods, then test a lower exit multiple. If returns fall, the investment case relies heavily on expansion rather than operating performance.
Show add-on acquisitions and dividend recaps separately, not as ordinary EBITDA growth or debt paydown. An acquisition can change EBITDA, enterprise value, debt and sponsor contributions; a recap can add borrowing and return cash to investors. Link the effects to sources and uses, include the relevant cash flows, and disclose how the bridge allocates any overlap for reconciliation with returns.
No. Attribution allocates modelled changes under assumptions; it cannot establish that management caused the return. EBITDA may rise because of market demand, acquired operations or factors beyond management decisions. Describe the bridge as an analytical explanation, state its convention and limitations, and support performance claims with operating evidence, including revenue, margin and cash-flow trends over the period.